2024年6月25日星期二

【理財新世代】樓市寬鬆措施技術調整與港樓前景 20240622

 2024年6月22日


主題:


》金管局上周宣布,2月底提出的再調整周期宏觀審價監管措施,擴大涵藍範圍至「撤辣」前簽臨時買賣合約嘅自用業主,而按證保險公司將相應將按揭保險計劃現時合資格準則亦相應擴大適用範圍,令有需要買家可以申請最高七成按揭,希望為面對估價不足而要補差價上會做按揭嘅業主紓壓,用意明顯係要幫呢一班業主?


》但衣家呢個問題嚴重性係米已經去到連金管局都要出手的地步?
根據粗略統計,呢兩年買左樓花,選擇用建築期付款嘅買家比例都多,根據政府數據,截至5月,待審批樓花盤有27個,樓價未見有起色,新盤劈價影響一手樓佔價,樓花盤準業主要補估價差額上會個案會愈嚟愈多?今次措施實際上幫到幾多?


》劈價潮對香港樓市的影響?到底會令香港樓市健康定會無幫助?


》除了金管局出招幫手,嚟緊息口走勢又幫唔幫到手?市場料美國今年減息至少一次,香港跟減機會大唔大?減一次幫得幾多?


報導來源:香港電台【理財新世代】

https://www.rthk.hk/tv/dtt31/programme/investmentera_tv/episode/899962


特此鳴謝


主持: 黃瑋傑、徐家健


攝影及剪接: 香港電台公共事務組

2024年5月31日星期五

SGP - Is Retail Property Price Peaking? 20240531

The combined favourable factors from capital flight due to the Ukraine/Middle East wars and HK's new national security legislation regime have massively pushed up investment demand for Singapore assets, thereby prompting headlines such as these of late:

>> Jack Ma's wife buys shophouses in ...Tanjong Pagar for $37m (article 1);

>> Bridgewater founder Ray Dalio joins billionaires snapping up Singapore ‘shophouses’ (Article 3)

>> Singapore’s shophouses — hotter than Fifth Avenue? (Article 4)

Whilst the first two headlines might be interpreted as 'smart money' making early moves, the last piece could be read as a sign of peaking market...

We continue to forecast a new macro environment that is different from the good old days of near zero interest rates and continued growth in global trade and productivity gains. Instead, we believe the new reality is one of decoupling, deglobalisation, and debt defaults, thanks to geopolitics and net zero / pandemic measures which not only will drive further inflation, but will undermine high economic growth.

One of the consequences of the combined higher for longer inflation and debt default scenarios is rates staying high, or return to 90s highs, if not even 80s high levels:

Above SGP interbank rates have already broken out of both the blue down trend as well as the lower horizontal resistance over the past two years. If the worse outcome does pan out as we feared, it might not be inconceivable to see rates hit 6.8% or thereabouts in the next 2-3 years.


If Rent/Price moves can't match rate rises?

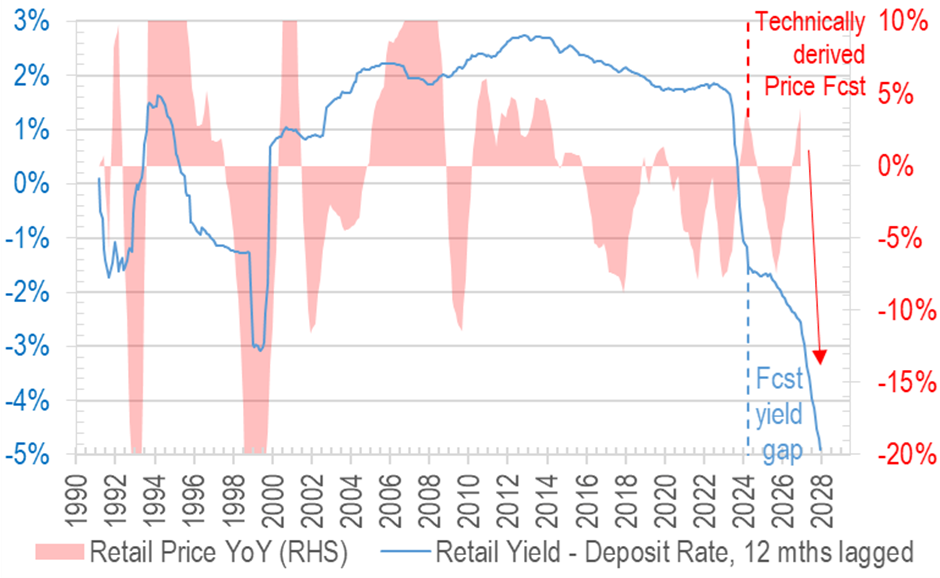
Using current trajectories in rent and price, we have modeled the near term yield increases, but sadly the rise in yields are not enough to offset the much more dramatic interest rate hikes, resulting in one of the more dramatic widening in retail yield discount vs deposit rates:

As a thought experiment, we believe this is probably as bad as it gets, because we are not factoring in the other capital flight which drove the rates higher - that from bonds. Perhaps the initial crack in bond market (when yields go north of 6%) will be negative for properties, but soon afterwards, the flight from bonds to real assets (may unfold as early 2026) will completely reverse price performances to the upside once more.

Based on this scenario, we think not all investors need to sell their safe haven assets (and indeed SGP shophouses are definitely safe haven in the world we live in now), if they can tolerate the price drops that happen before the final phase of the upcoming yield expansion cycle...

In the meantime, the very anaemic returns on retail property in SGP will continue to be a pain to tolerate, especially for leveraged up owners:


Could SGP retail further outshine HK in next few years?

The above wide gap between yield and funding cost does indeed support our near term bearish outlook on SGP retail assets, but if you look at the technicals vs HK retail property, SGP retail has broken out of the green downtrend, and could be hitting the blue channel top very soon (24% outperformance):

Should that level be also breached, there could be even more upside to the top red resistance (another 135% upside?).

Such a scenario probably can only unfold if HK retail see another major leg down, and that could only be driven by geopolitics rather than vanilla macro economics...


==================Article 1==================

Jack Ma’s Wife Buys Shophouses in Singapore’s Tanjong Pagar at Up to $37M

Beatrice Laforga | 2024/02/23

Despite stamp duties and investigations, wealthy mainland investors are still banking on Singapore properties, with the wife of the country’s best known tech tycoon having purchased a row of shophouses in the Tanjong Pagar area last month for a reported S$45 million to S$50 million ($33.5 million to $37.2 million).

https://www.mingtiandi.com/real-estate/finance/jack-mas-wife-buys-shophouses-in-singapores-tanjong-pagar/

==================Article 2==================

Shophouse sales surge and at higher prices in Q1 as high-net-worth investors return: Knight Frank

Samuel Oh | Fri, May 10, 2024 · 10:38 AM

In 2023, shophouse sales came to 132 units worth S$1.2 billion. The number of units was 31 per cent lower than the 191 units transacted in 2022 worth S$1.6 billion. Shophouse sales have fallen from their peak in 2021, when a total of 254 units worth S$1.94 billion changed hands.

[...]

Knight Frank projects the sales volume of shophouses to be between S$1.1 billion and S$1.2 billion for the rest of 2024.

​https://www.businesstimes.com.sg/property/spotlight-1/shophouse-sales-surge-and-higher-prices-q1-high-net-worth-investors-return-knight-frank

==================Article 3==================

Bridgewater founder Ray Dalio joins billionaires snapping up Singapore ‘shophouses’

Investor’s family office bought two heritage properties for $19mn

Bridgewater Associates founder Ray Dalio’s family office has bought two multimillion-dollar “shophouses” in Singapore, as billionaires snap up the heritage properties in the city-state.

​https://www.ft.com/content/9741784e-f69a-45cf-adf3-cc5b863c873f​​

==================Article 4==================

Singapore’s shophouses — hotter than Fifth Avenue?

Mercedes Ruehl / MAY 24 2024

Amid changing political dynamics in South-East Asia, these colonial-era buildings have become some of the world’s most expensive properties, home to Michelin stars and chichi retailers — and a target for money launderers

https://www.ft.com/content/e1a53cb8-5bf0-408a-91a0-bcdd738c0f11

2024年5月29日星期三

Is the big rush into Japanese property justified? 20240529

We have heard nothing other than 'we are buying Niseko ski flat' or 'our fund is adding Tokyo hotel' for the past few months, as if the rest of the world is all in the dog house...

Clients familiar with our arguments will know we have been negative for at least 2 years on the Japanese market, so this email seeks to give a more rounded exposition on why.

When crowds scramble one way, we go the other

The recent scramble for adding Japanese exposure (see Article 1) is in line with the concurrent rise in the Topix, but in property land there is even more momentum, especially amongst funds:


Granted, funds have been sitting on their hands in the past 2 years as interest rates globally spiked, and their IRR calculations were thrown into disarray. So the wishful hope that Fed rate cuts will be implemented (now proven wrong), plus a reversal of Japanese asset depreciation has sparked a sudden fad into pumping money into the land of the rising (may be now setting) sun...

We are very wary of the much more significant risk of Yen devaluation against whatever puny asset appreciation in the currency in the coming years however, and would prefer other jurisdictions where BOTH currency and asset prices will rise (regular readers will know where that is!).


FX should be central in investment decisions

The point of making price gains but adding translation losses is best illustrated with a view to history:


As shown above, during the haydays of Japanese industrial and cultural ascent, both asset prices in local currency (LC) and exchange rates were on the rise - see left green arrow. The combined effect for foreign investors is even stronger returns in USD terms (red line) than locals (blue line), shown by the purple enlarging triangle.

In the subsequent lost 2 decades, Yen basically went sideways (2nd green arrow), with price drops very comparable in LC and USD (purple parallelogram).

We are now probably into the next leg of Yen derating (see 3rd green arrow) thanks to shrinking population - see Article 3 - and the resurgent commodities complex when all input materials see price spirals. Unsurprisingly, since 2010, despite LC price gains, USD denominated values fell (purple trapezium).

We expect the next (final) down leg in Yen (4th green arrow) to unfold in the next 3 years or so, which can also destroy value for overseas investors (ie down red arrow despite up blue arrow).

To put it in numbers terms, below is a table showing the impact of Yen weakness (red shades) vs USD denominated Tokyo home prices:

Of course, the 2025-29 projections above are purely based on the arrows in chart above and may not play out the way we projected, but the risk that you get negative USD returns (2nd column from right) is very real indeed.


Macro picture for Japan: far from rosy

By the combined will to reintroduce inflation and to inflate away the mountains of govt debt (highest in OECD), the Japanese work force has been earning negative real income for the past two years:

In the meantime, the cost of living crisis left private consumption down for 4 quarters in a row, with little help to exports (net exports were increasingly negative in recent quarters) to contribute to GDP growth:


In the meantime, the geopolitical tensions between China and US is causing the rate environment to surge further, due to:

1) loss of demand for US debts by big traditional owners like China (fr 8.9% to 2.2% in 13 yrs) and HK, in fact Japan has also been falling in total proportion of US treasury holdings (fr 9.5% to 3.4% now):


2) Ukraine/Middle East conflicts likely to trigger more input price inflation, eg oil prices - and as a resource poor but manufacturing intensive economy, higher oil prices (blue line, down is higher prices) will tend to trigger economic contractions (red area). The green line is merely projecting prices returning to $150/barrel, which can easily be exceeded should international wars flare up again:


The result would be grim for Japanese economy. If wars spread to the APAC region, there is an added strong chance of capital flight from Japan given its recent militarisation movements might scare foreign investors away:


3) bond rout will impact Japan more than US - as US fiscal profligacy continues (yes, by adding $3.5tr debt in one year), long bond yields have nowhere to go but up (orange line), this will drag JGBs up with it (green line). Assuming totally benign geopolitical/sovereign debt calm conditions, the laughable 0.87% JGB yield will still nearly triple to 2.5%, and this 'benign' expansion of US-JP yield spread may trigger further capital outflows as money seeks higher returns in the US:


The result? Yen could drop another 25% to the 200 mark.

If this Yen drop becomes disorderly, it could result in JGBs trading at premium to TBs, leading to the much more nightmarish outcome of 10.5% JGBs vs say 8.5% TBs:


Such an outcome would mean Yen has to return to 270+ levels, much against the wishful sub-150 levels the 'anchoring biased' talking heads out there could imagine... or a 45%+ drop from current levels.


Real yields also too low to be attractive

Back to our usual real property yield table - Sydney/Singapore/Tokyo are some of the lowest returning markets on inflation adjusted basis (3rd column from right), compared to Phnom Penh/Athens which are our preferred investment destinations:


In a bond rout outcome, both European and Japanese markets will suddenly look much worse as US becomes the safe haven, thereby helping HK/NYC (2nd column from right).

Based on these various factors, we will only touch Japan if: a) long term fixed rate borrowing can be locked in; b) Yen leverage and/or hedge are put in place. But how many even the big institutions are taking these precautionary measures? We doubt many. On this note it is interesting to demonstrate how institutions are mere humans, however smart they otherwise appear: see Article 2.


==================Article 1==================

Interest in Japanese real estate grows despite rate rise prospects

Mar 8, 2024

Institutions and family offices are backing real estate for another strong year, despite the prospect of the country’s first interest rate rise since 2007.

​https://www.asianinvestor.net/article/interest-in-japanese-real-estate-grows-despite-rate-rise-prospects/494795​


==================Article 2==================

Hidden billions in Tokyo real estate lure activist hedge funds

Apr 16, 2024

The long-concealed market value of Tokyo’s largest skyscrapers is being unveiled by activist investors.

​https://www.japantimes.co.jp/business/2024/04/16/companies/headge-funds-urge-japan-real-estate-sales/​

==================Article 3==================

Japan’s Population Declines Again: Seniors 75 and Over Top 20 Million for First Time

Apr 24, 2024

An estimate published by Japan’s Ministry of Internal Affairs and Communications shows that the total population as of October 1, 2023, was 124,352,000. This was a drop of 595,000 (0.48%) from the previous year. It is the thirteenth consecutive year that the population decreased. The population of Japanese citizens was 121,193,000, for a record year-on-year decrease of 837,000, or 0.69%.

​https://www.nippon.com/en/japan-data/h01967/

2024年4月30日星期二

【Metro Radio】 新城財經台 新城地產街 20240429

 載於2024年04月29日 【Metro Radio 新城地產街】 

主題: 

》二月撤辣後樓市現況?發展商積極推盤,當中銷售情況有何反映?但市場形容開價並未進取,為何出現有關情況?

》美國今年是否能夠在年底前減息,仍然存在變數,如何看減息機會?高息環境已持續一段時間,對入市意慾影響如何?

》股市低迷,加上零售消費市道疲弱,無財富效應下,對樓市影響?經濟與樓市關係?

》過去幾年政府都積極賣地,加上發展商仍有不少貨尾單位,現時供求情況如何?未來潛在供應如何?在粵港澳大灣區下,本港未來定位及角色?


嘉賓: 

Bricks & Mortar Management 主席兼總裁 王震宇

紀惠集團行政總裁 湯文亮

嘉賓主持:

國眾聯測量師行顧問 余錦雄


新城連結:Bricks & Mortar Management 主席兼總裁王震宇


2024年4月23日星期二

過江龍一舉南下 本地薑大難臨頭? 20240423

本文亦於2024年4月23日在【信報】刊登: 過江龍一舉南下 本地薑大難臨頭?


港人北上消費近來成為城中熱話,連各大傳媒亦爭相報道(如南華早報和紐約時報)。當然港人外遊的新趨勢絕不僅限廣東,在2020-2023年疫情封關後報復性消費和強港元之配合下,日本、東南亞等熱門目標同遭淪陷。

港人愛嘗新亦貪平,更追求高質服務;此一高消費市場當然不會被野心勃勃內地品牌忽視,難怪越來越多的新食肆在過去數月如雨後春筍般遍地開花(見星島日報),筆者隨手拈來已可於網上搜到眾多例證。

南下內地品牌到底能在本港造成多大影響?筆者且由《2023年中國百大品牌》名單(覆蓋了全國約22萬門店)出發,探索各大內地連鎖食肆來港開業的規模會有多大。

各大菜系分佈:川粵掄元

透過分析以上餐飲連鎖店菜餚和食品類型,不難一窺現代中國城市人的飲食品味。先以菜系排列,川菜以經營連鎖店數量最多取勝(16間品牌),其次為飲品類別(13間),粵菜再次之:

圖一:中國百大品牌/門市-依菜系劃分

若以門市數量而言,川菜亦位居第三(上圖橙色標記),排在第一名的飲品及第二名的美式菜系之後。如單計中菜,則川菜門市穩坐第一,繼而湘菜。

綜合而言,約百分之30的百大品牌專注於川菜及粵菜。然而最出奇的卻是,魯菜和蘇菜雖與川粵同列於「中國八大菜系」,卻在上圖中敬陪末席,分列23名和19名!

小菜與速食在食物種類中稱霸

可能中式飲食實在太過千變萬化,加上食客無疑口味多元,因此小菜類別位居榜首(見藍色棒)。這種勞力密集的烹調過程應該導致小菜類食肆以小型連鎖店為主,更不用說數以萬計不上榜的家庭式餐廳。

排於其後的幾乎全為易於量產的快餐類食品,如火鍋、飲料、快餐、漢堡、意式薄餅等:

圖二:以食品類別排名-主要爲速食品種

同樣不足為奇的是,快餐類門店(即:手搖飲品、中式快餐、炸鷄、鹵味等)因為週轉快、銷量大帶來的規模經濟,在門店數量排名中名列前茅(上圖橙色標記)。

菜系分佈:爲何粵菜分店比例出奇地低?

儘管粵菜新鮮、創意十足且早已風行世界,但在百強榜上分店比例相對其他菜系卻出奇地低:

圖三:品牌占比與分店占比-快餐類的高滲透與粵菜的低市佔率

從上圖可見,粵菜的品牌數目占比與分店數目距離甚遠。如此意想不到的分佈可能歸因於粵菜需要更多新鮮食材(大多由華南溫暖地域供應),及更多海鮮菜餚亦令內陸開店增加難度,此外粵菜需要較多的烹調技術(如以煎炒為主,烤燉為副),以至限制了粵菜厨師的供應,從而減低粵菜分店的數目…

食品類別分佈:飲品和快餐遍地開花

以食品種類分析,不難見到即叫即做的餐飲(如小菜類,見下圖紅色標籤)雖品牌眾多,卻難敵流水線式大量供應類別的食品(如快餐,見藍色標籤);可見降低餐牌的複雜性以增加產量,是快速增長品牌的滲透率的不二法門:

圖四:品牌占比與分店占比—快餐滲透最強


深圳和上海佈局與全國平均何異?

接下來,筆者探討眾品牌是如何在一線城市(上海和深圳)插旗,以及是否有某些板塊仍有大展拳腳的機會。

有趣的是,上海開店比例較全國為高的品牌(下圖紅色標籤)似乎以香港上市公司為主,可能因其較早進入市場及有資本市場融資打本兩大優勢。在另一極端,上海相對全國滲透率較低的品牌往往是地方性的小品牌,因為具有較低聲望或市場推廣而令其較難以躋身上海—即以人口比例計應有門店數量遠高於實際開店數量(如霸王茶姬和書亦燒仙草):

圖五:上海—全國人口比例應有分店與實際數目對比

而深圳的佈局則更爲有趣:本地品牌和地方菜式滲透力極強,如客家菜及粵菜品牌比例奇高(可能印證上文所說的菜系優勢),另外高滲透的品牌亦皆為本地企業(即木屋燒烤和真功夫):

圖六:深圳—全國人口比例應有分店與實際數目對比


香港飲食新境界:新品牌開張潮方興未艾

撇開香港餐飲是否已經達至飽和者事實,大量內地品牌或應會將之視為未來增長目標,亦因香港的國際城市地位而必須在此插旗以增聲價。可以肯定未來國內頂級餐飲品牌將繼續大舉南下來此開業。

然而品牌流入的數量又如何推算呢?由於香港和上海都是門戶城市,因此以上海品牌滲透率做指標不難計算出可能會在本港開業的品牌及最終分店數目;以下是筆者推算的結果:

圖七:香港—以上海人口估算的分店數目相對現有實際數目

出人意表地,以上海分店/人口比例估算,大家樂的分店數量似乎已經過度飽和,甚至需要削減在港的佈局。仍然,取而代之的是數十間百大餐飲來港開市,如【圖七】左整排橙色標籤所示。這意味著未來數月至數年間將有數百家內地餐飲新店進駐香港——圖上面的細箭頭暗示每個品牌可能最終會在港擁有超過10家門店,而圖下粗箭頭則意味這些品牌每間都為本港帶來單位數新店。

將上海滲透率加諸香港後,不難得到以下開/關分店數量的排行榜:

圖八:香港—國內品牌入場離場可能性(頭十及尾五名)

推算結果預示本港將會有海量的新飲料店開張:單是上圖四大品牌已愈340家分店之數!當然,計量分析以外的因素不可不顧:例如,香港本地咖啡店的滲透率是否已經令茶啡類經銷點飽和?在當下「工匠咖啡」館充斥的年代,市場還有多大空間容納瑞幸咖啡呢?本土傳統涼茶又是否會消減喜茶等內地大眾茶飲品牌的需求?

新品牌進駐的反面,則是某些在港的品牌可能須要關舖的可能,例如專營鴨脖的絕味(?!),甚或本地的大型連鎖店大家樂等。隨著新品牌進駐,必會有一班食肆面對客戶流失的命運。

南下餐飲對零售樓面需求—多多益善,少少無拘

此一浪新品牌開擴本港飲食市場的熱潮到底將帶多少額外零售樓面的需求呢?以上來自前100名品牌的新入場者大約會創造55萬呎的需求,相對於香港1.3億呎的零售存量似乎只是九牛一毛(僅增加0.45%而已)。儘管如此,作為消費者港人應該樂見新的產品增加購物選擇並引入新的飲食方式,亦進一步提升香港「美食天堂」的聲譽。


筆者特別鳴謝香港城市大學金融學系楊清華同學協助收集及整理本文相關數據及圖表。